Open Banking in Poland: Coverage and Provider Fit
Poland is where many EU payment roadmaps add Central Europe — a large banked population, fast mobile adoption, and heavy use of bank transfers for B2B invoices — yet open banking Poland on a provider slide rarely matches what your customers experience in production. Coverage gaps, corporate account quirks, and BLIK habits all show up in conversion and reconciliation metrics, not in marketing maps. This guide explains what Polish open banking delivers for B2B teams, how it relates to BLIK and wider EU instant-payment work, and which provider evaluation questions matter before you commit budget.
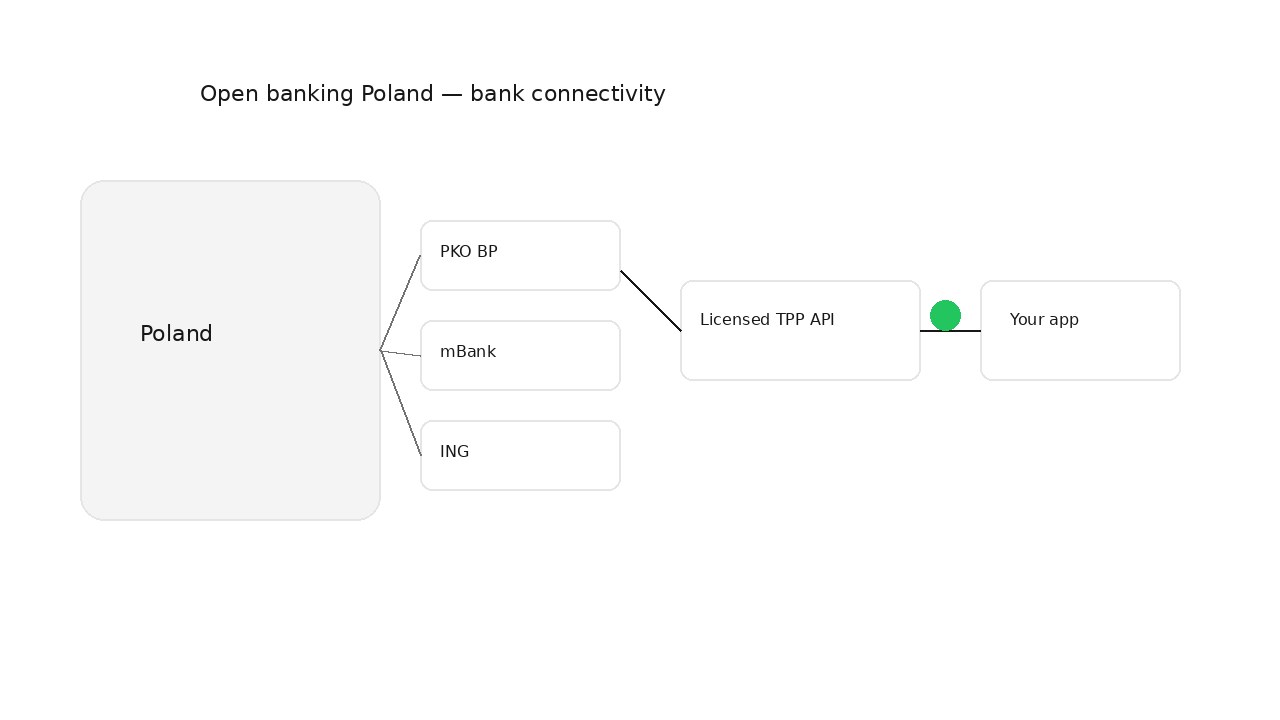
Open banking in Poland: Connecting to Polish banks through regulated EU payment APIs so your business can verify accounts, initiate customer payments, read consented transaction data, and reconcile cash — with customers approving access in their banking app.
For how Poland fits a wider EU rollout, see open banking UK vs EU. For Western EU comparators, cross-read open banking Germany and open banking Italy.
Why Poland is a priority market — and a distinct one
Polish buyers and businesses already settle invoices, rent, and supplier payments by bank transfer. Open banking productises that behaviour: instant confirmation at checkout, verified IBANs at onboarding, and structured feeds for finance instead of PDF uploads.
What makes Poland distinct for integrators:
- Concentrated retail banking — PKO Bank Polski, mBank, Santander Bank Polska, ING Bank Śląski, Bank Millennium, and Alior Bank drive most consumer volume; winning them matters more than long-tail checkboxes
- BLIK as a local habit — mobile push-to-pay is deeply familiar; customers may expect BLIK-like speed even when you run PSD2 Pay by Bank
- Strong mobile banking — authentication often completes in the banking app, which helps Pay by Bank UX when flows are mobile-first
- B2B transfer culture — business accounts and structured payment titles differ from consumer salary accounts; verify corporate coverage explicitly
- SEPA Instant growth — instant settlement helps marketplace payouts and treasury when bank pairs support it, but participation still varies by institution
Poland-strong is not EU-strong. Treat Germany, France, or the Nordics as separate acceptance tests even if your contract says “Europe.”
Open banking vs BLIK — what B2B teams need to know
Open banking pay by bank uses PSD2 APIs through licensed providers; BLIK is Poland’s dominant mobile payment brand — related consumer rails, different merchant integration paths.
The European Banking Authority sets the EU-wide payment-services framework that Polish open banking implements nationally. BLIK, operated by Polski Standard Płatności, sits alongside those APIs as a scheme customers already trust for mobile checkout. For B2B product and payments leads today, the practical split is:
| Dimension | PSD2 open banking (Pay by Bank) | BLIK / scheme wallets |
|---|---|---|
| Integration | Licensed TPP API — you control checkout UX and reconciliation | Scheme or bank-app flows — often consumer-facing, less merchant API control |
| Use cases | Checkout, verification, lending data, B2B invoice collection | Domestic mobile habits, e-commerce BLIK checkout, P2P |
| Coverage test | Named Polish ASPSPs via provider sandbox | Whether your customers expect BLIK buttons vs generic bank redirect |
| Reconciliation | Webhooks and references you design | Scheme-specific settlement reporting as features roll out |
Most EU platforms serving Poland run dual awareness: merchant-initiated open banking for controlled checkout and verification, plus a roadmap view on BLIK where consumer habits demand it. Do not assume one local scheme replaces PSD2 sandbox work on your bank list.
What Polish open banking is used for in B2B
Teams operating in Poland typically prioritise these outcomes:
| Use case | Business outcome |
|---|---|
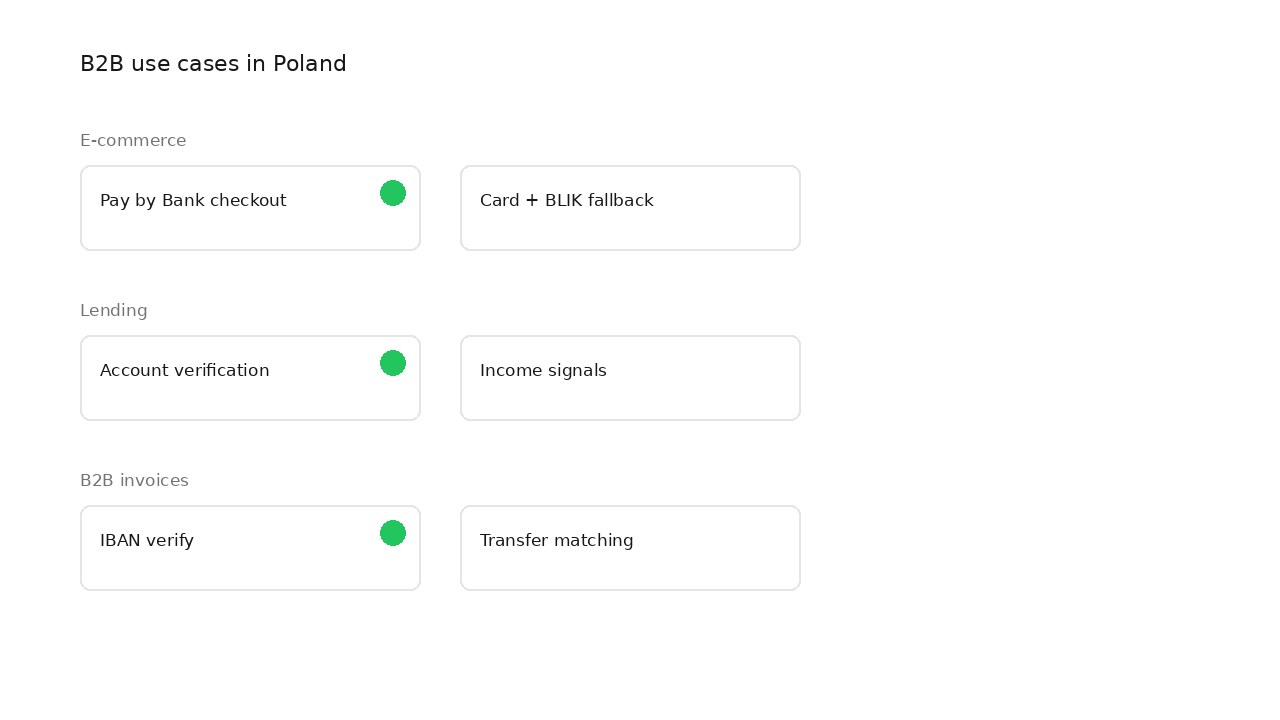
| Pay by Bank checkout | Lower cost per payment and immediate confirmation on eligible flows |
| Account verification | Fewer wrong-IBAN payouts and onboarding fraud |
| Invoice and B2B collection | Match incoming transfers to invoice IDs faster |
| Lending and onboarding | Bank-verified income and affordability — see open banking for lending |
| Marketplace payouts | Seller disbursement over SEPA with verified accounts |
| Recurring collection | First payment via bank app, renewals via SEPA Direct Debit where supported |
Retail-framed guides like open banking for e-commerce and pay by bank apply rail mechanics; Polish B2B teams add NIP/REGON checks, ERP reconciliation, and corporate payer workflows on top.
Coverage: how to read provider claims honestly
Marketing materials cite thousands of banks across Europe. For Poland, ask narrower questions:
- Which Polish institutions cover >80% of your user base? — list PKO BP, mBank, ING, Santander Polska, Millennium, and the neobanks your data shows, not percentage alone
- Retail vs business accounts — does verification and payment initiation work on the account types you onboard?
- Redirect vs embedded UX — what does the customer see on mobile for each major bank?
- Downtime history — incident transparency for the groups you actually see in production data
- Instant vs standard SEPA — when SCT Inst fails, what fallback timing do you communicate to treasury?
Run sandbox tests with real internal accounts at your top ten customer or borrower banks before shortlisting vendors. A provider optimised for UK open banking will not automatically feel native in Poland.
Regulatory context in plain terms
Polish open banking sits on EU payment rules implemented nationally — customers must consent, strong authentication applies for access and payments, and regulated providers hold the licences to call bank APIs on your behalf. The European Banking Authority maintains the EU framework; Narodowy Bank Polski supervises financial stability and payment-system oversight in Poland.
The ECB’s October 2026 step toward digital euro infrastructure (Finextra summary of ECB network provider selection) does not replace PSD2 open banking for merchants today — it is parallel EU rail planning. B2B buyers should still validate Polish ASPSP coverage on current APIs.
For B2B buyers this means:
- You usually integrate a licensed partner rather than becoming a payment institution on day one
- Purpose and consent copy must match what you do (checkout vs lending vs verification)
- Data residency expectations are stricter in enterprise procurement — confirm EU hosting and subprocessors
This is context for procurement, not a substitute for legal review.
Provider evaluation questions for the Polish market
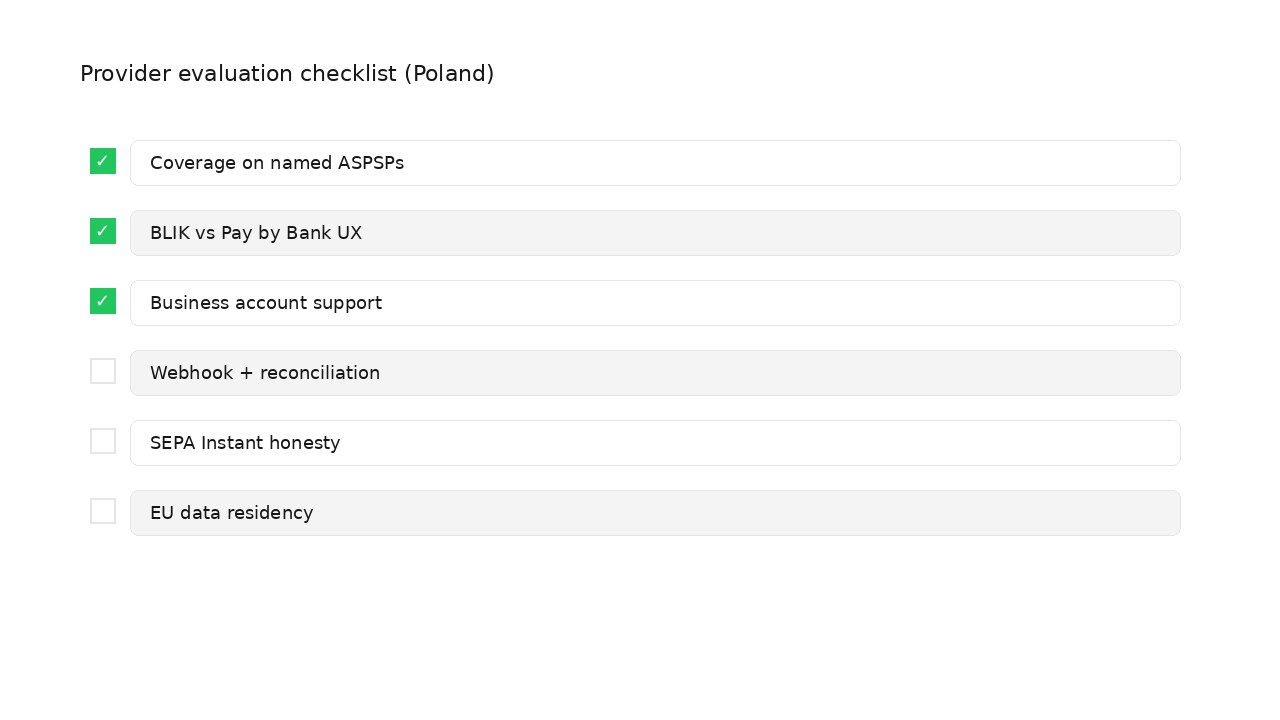
Use this checklist in RFPs and technical diligence — score answers with evidence, not slides. If you need a structured shortlist across markets, use our provider matching form to compare coverage for your bank list and use case.
Coverage and reliability
- Name the top 15 Polish ASPSPs you support in production, with go-live dates
- What is your measured success rate for payment initiation on those banks (last 90 days)?
- How do you handle bank maintenance windows and degraded modes?
Products your roadmap needs
- Pay by Bank: mobile deep links, QR, desktop redirect behaviour per major bank
- Account verification: name–IBAN match rates on retail and business accounts
- AIS depth: transaction history length, categorisation for lending or reconciliation
- Payouts: outbound SEPA and Instant coverage for marketplace or lender disbursement
- Recurring: SEPA Direct Debit mandate support after first authenticated payment
Integration and ops
- Sandbox parity — do Polish banks in sandbox match production behaviour?
- Webhook delivery guarantees, retries, and signing for finance automation — see open banking webhooks
- Reference field rules compatible with Polish invoice numbers and ERP imports
- Support SLAs in CET business hours for production incidents
Commercial and risk
- Pricing model for successful vs failed initiation attempts
- EU data residency, ISO 27001 / SOC 2, and subprocessors list
- Sector acceptance: marketplaces, lenders, insurers, SaaS — named in contract
- Exit terms and portability if you change provider after go-live
No single vendor fits every Polish use case; matching depends on whether you optimise checkout conversion, lending data depth, or B2B payout reliability. See how to choose an open banking provider for a cross-market framework.
Common Polish deployment patterns
E-commerce and marketplaces — Pilot Pay by Bank on high-AOV PLN baskets with card fallback; add seller verification before scaling weekly payouts. Cross-read open banking for marketplaces.
SaaS and B2B platforms — Verify the account on annual invoice setup; collect first payment via bank app; move renewals to direct debit where mandates are supported. See open banking for SaaS platforms.
Lenders — Income verification on supported banks first; expand affordability and collections once consent renewal is automated. See income verification open banking.
Multi-market EU expansion — If Poland follows Germany or the Nordics in your rollout, treat each country as a separate acceptance test. Open banking providers Nordics shows how geo-specific diligence differs from a single “EU” checkbox.
Frequently Asked Questions
What is open banking in Poland?
Open banking in Poland is regulated API access to Polish bank accounts so businesses can verify accounts, initiate customer payments, and read consented transaction data — with customers approving in their banking app, usually via a licensed provider that connects to major Polish ASPSPs.
Is open banking widely used in Poland?
Adoption is growing for Pay by Bank and account verification, but BLIK, cards, and long-standing bank-transfer habits still shape many payment flows. Pilot on your customer bank mix rather than assuming Poland behaves like the Netherlands or the UK.
What is the difference between open banking and BLIK in Poland?
Open banking uses PSD2 APIs through licensed providers for merchant-controlled checkout, verification, and data access. BLIK is Poland’s dominant mobile payment scheme — strong for local e-commerce and P2P habits, but not a drop-in replacement for merchant API integration today.
Do I need a Polish licence to use open banking?
Most non-bank businesses integrate a licensed open banking provider that holds the required EU authorisations. Your legal team confirms whether your specific model needs additional licensing beyond that partnership.
How is Polish open banking different from Germany or the Nordics?
All operate under EU payment rules, but Poland combines concentrated banking groups, BLIK mobile habits, and heavy B2B transfer culture — different from Germany’s Sparkassen invoice patterns or Nordic real-time schemes. Test each market independently.
Which Polish banks matter most for coverage?
Depends on your segment — consumer lenders care about retail neobanks and major high-street groups; B2B invoice platforms care about professional account support. List the banks your users actually hold and test those in sandbox, prioritising PKO BP, mBank, and ING unless your data says otherwise.
Can open banking replace cards in Poland?
For many flows it supplements rather than replaces cards — especially where customers expect BLIK or card habits or international buyers use non-Polish banks. Most teams run dual rails with data-driven routing.
How do I evaluate open banking providers for Poland?
Demand named bank coverage, sandbox proof on your top institutions, success-rate data, business-account support, Instant payout honesty, EU hosting, and sector fit in contract. Weight criteria by your primary use case — checkout vs lending vs payouts.
Closing thought
Open banking Poland rewards specificity: name the banks your customers use, understand BLIK as parallel consumer context, and separate marketing coverage from production success rates. Once Polish flows work, expand to the next EU country with the same discipline — not the assumption that one “EU” integration behaves identically everywhere.
Related articles
- Open Banking in Italy: Coverage and Provider Fit
Italy is where many EU payment roadmaps add Southern Europe — large retail banks, strong mobile banking, and heavy use of bank transfers for B2B invoices — yet…
- European Network for Payments: What ENP Means for Merchants
Cross-border checkout still fragments when every country ships its own bank-app wallet — Spanish shoppers live in Bizum, Nordics in Vipps MobilePay, and Wero k…
- Open Banking in Spain: Coverage and Provider Fit
Spain combines one of Europe's strongest account-to-account payment cultures with an open banking stack that looks nothing like the UK's single-standard model.…