Open Banking in Spain: Coverage and Provider Fit
Spain combines one of Europe's strongest account-to-account payment cultures with an open banking stack that looks nothing like the UK's single-standard model. Open banking Spain on a provider slide rarely matches what your customers experience at checkout or onboarding — Redsys gateway quirks, Bizum's parallel consumer rail, and card-heavy e-commerce habits all show up in conversion data, not marketing maps. This guide explains what Spanish open banking delivers for B2B teams, how it differs from Bizum, and which provider evaluation questions matter before you commit budget.
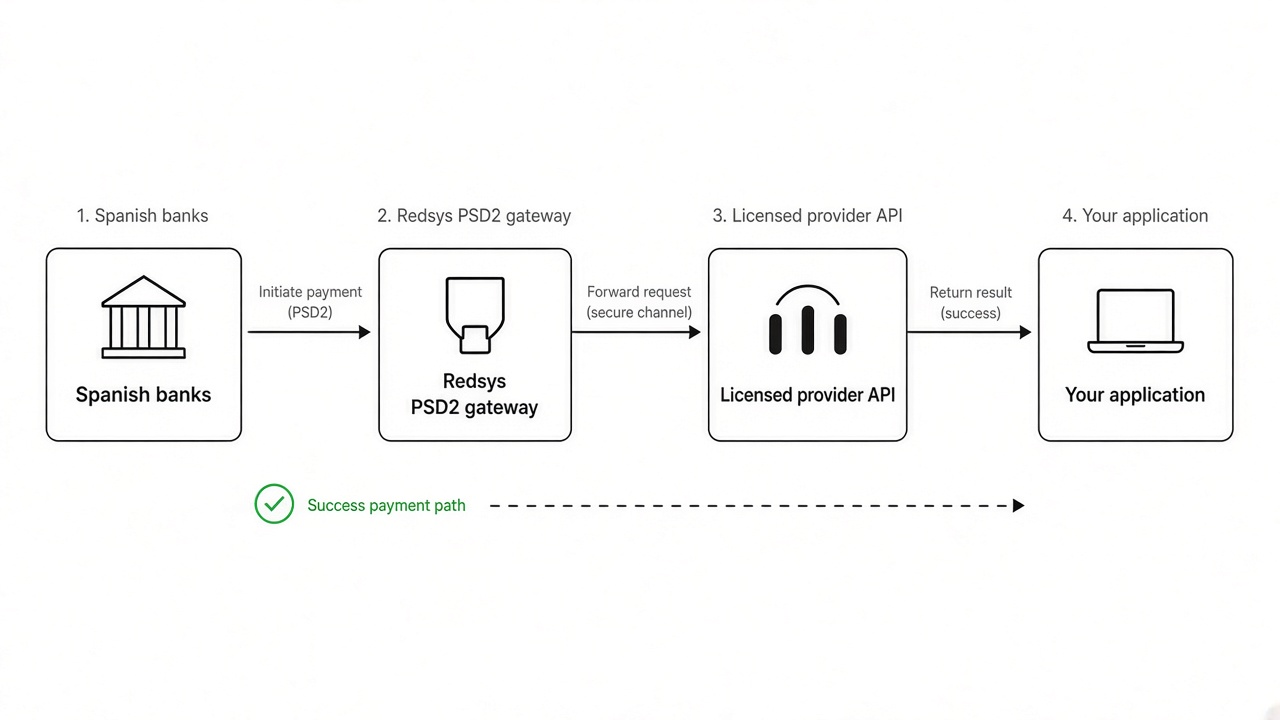
Open banking in Spain: Connecting to Spanish banks through regulated PSD2 APIs — often via the Redsys gateway — so your business can verify accounts, initiate customer payments, read consented transaction data, and reconcile cash, with customers approving access in their banking app.
Why Spain is a priority market — and a distinct one
Spanish buyers already pay by bank transfer for rent, utilities, and B2B invoices. Open banking productises that behaviour: instant confirmation at checkout, verified IBANs at onboarding, and structured feeds for finance instead of manual statement uploads.
What makes Spain distinct for integrators:
- Redsys as de facto gateway — many Spanish banks expose PSD2 APIs through the Redsys platform using Berlin Group-style interfaces, rather than each bank publishing a fully independent API surface (Mastercard open banking analysis)
- Bizum as parallel consumer rail — the bank-backed instant scheme dominates P2P and is expanding in-store; it is not the same product as merchant-initiated PSD2 pay by bank, but customers expect to recognise the brand
- High SCT Instant adoption — Iberpay incorporated SCT Inst early; Spanish participants cover most domestic payment volume, which helps instant settlement when bank pairs support it
- Card-heavy e-commerce — online card share remains high compared with the Netherlands; Pay by Bank wins on cost and authentication when UX is mobile-native, not when it feels like an admin chore
- Concentrated retail banking — CaixaBank, BBVA, Santander, Sabadell, Bankinter, and ING España drive most consumer volume; neobanks matter for younger segments
Spain-strong is not EU-strong. Treat France, Germany, or the Nordics as separate acceptance tests even if your contract says "Europe." Cross-read open banking France, open banking Germany, and pay by bank Netherlands when planning multi-market rollouts.
Open banking vs Bizum — what B2B teams need to know
Open banking pay by bank uses PSD2 APIs through licensed providers; Bizum is a bank-backed instant scheme accessed via consumer banking apps — related rails, different integration paths.
Bizum grew from peer-to-peer transfers and now reaches into e-commerce and physical retail. On 21 September 2026, Bizum reported that in-store payments were available to 20 million users — about 60% of its user base — with 75% of bank payment terminals and more than 1.6 million merchants accepting the scheme, according to Europa Press citing the company's statement.
For B2B product and payments leads, the distinction matters:
| Dimension | PSD2 open banking (Pay by Bank) | Bizum |
|---|---|---|
| Integration | Licensed TPP API — you control checkout UX and reconciliation | Scheme or bank-app flow — often consumer-facing, less merchant API control |
| Use cases | Checkout, verification, lending data, B2B invoice collection | Consumer P2P, growing retail and e-commerce acceptance |
| Coverage test | Named banks via Redsys/provider sandbox | Whether your customers expect Bizum vs generic bank redirect |
| Reconciliation | Webhooks and references you design | Scheme-specific settlement reporting |
Most EU platforms serving Spain run dual rails: merchant-initiated open banking for controlled checkout and verification, plus awareness of Bizum where consumer habits demand it. Do not assume one integration replaces the other.
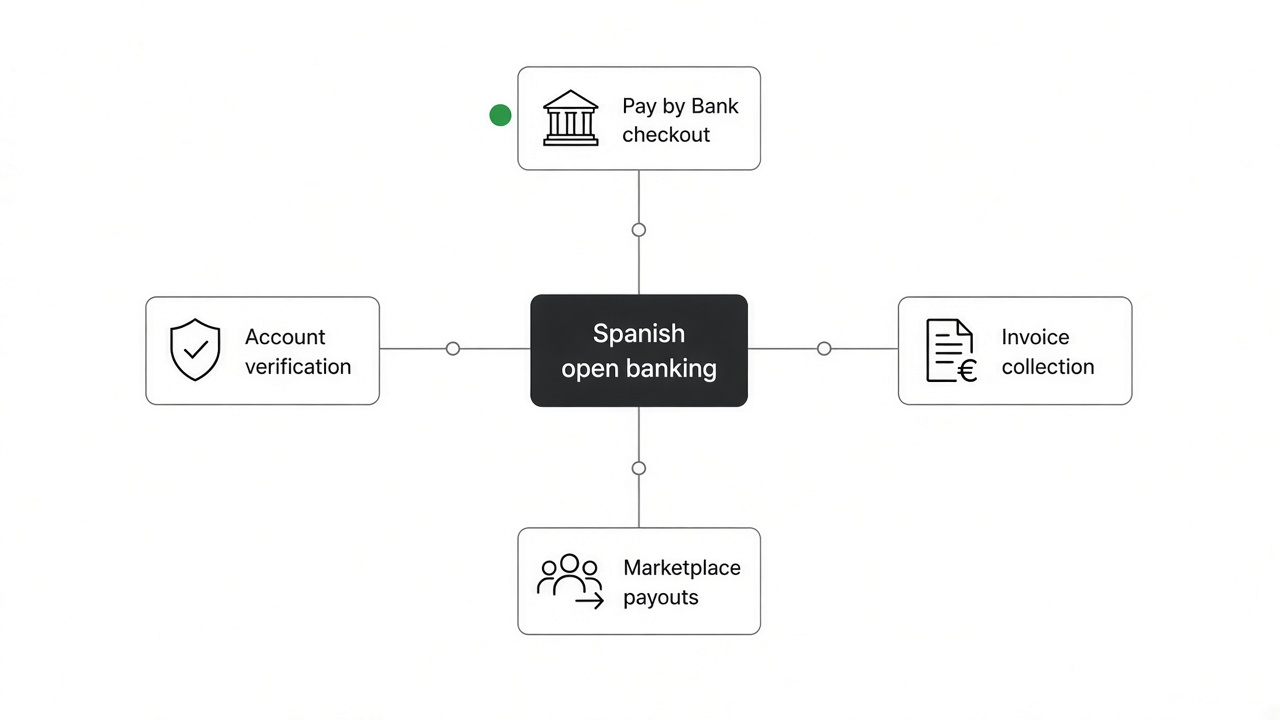
What Spanish open banking is used for in B2B
Teams operating in Spain typically prioritise these outcomes:
| Use case | Business outcome |
|---|---|
| Pay by Bank checkout | Lower cost per payment and immediate confirmation on eligible flows |
| Account verification | Fewer wrong-IBAN payouts and onboarding fraud |
| Invoice and B2B collection | Match incoming transfers to invoice IDs faster |
| Lending and onboarding | Bank-verified income and affordability — see open banking for lending |
| Marketplace payouts | Seller disbursement over SEPA with verified accounts |
| Recurring collection | First payment via bank app, renewals via SEPA Direct Debit where supported |
Retail-framed guides like open banking for e-commerce and pay by bank apply rail mechanics; Spanish B2B teams add invoice references, ERP reconciliation, and corporate payer workflows on top.
Coverage: how to read provider claims honestly
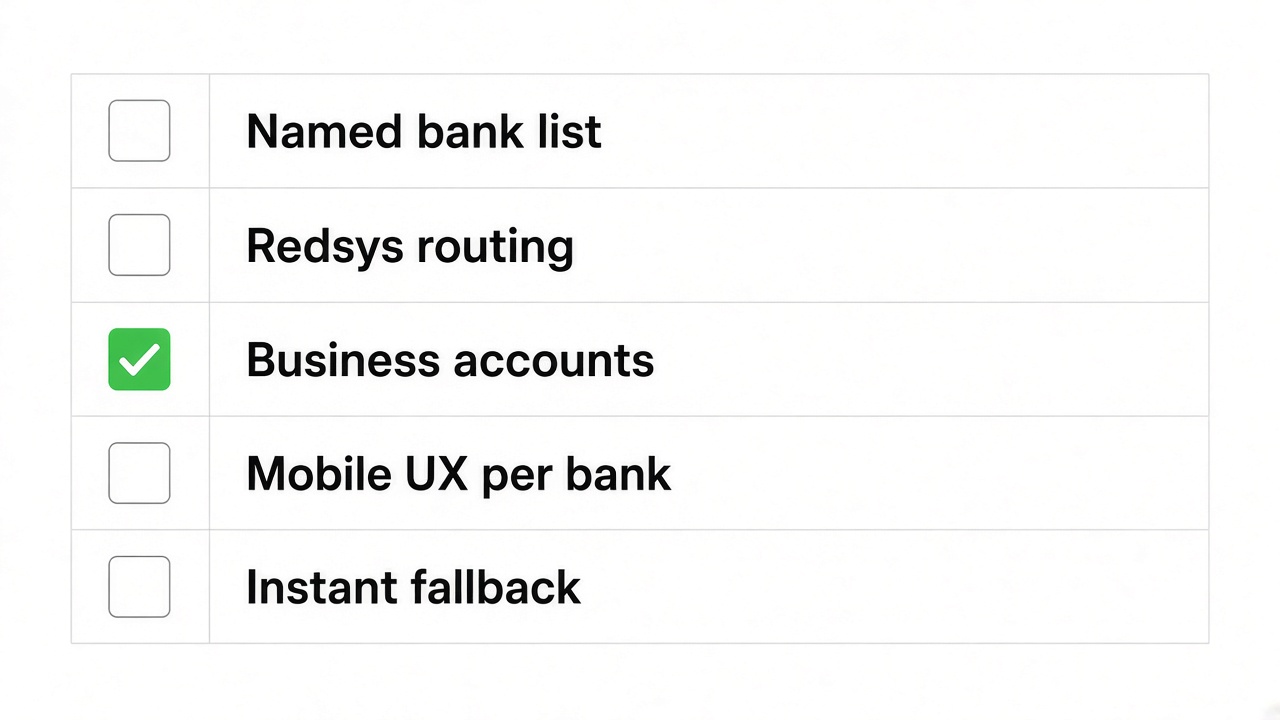
Marketing materials cite thousands of banks across Europe. For Spain, ask narrower questions:
- Which Spanish institutions cover >80% of your user base? — list CaixaBank, BBVA, Santander, Sabadell, Bankinter, and the neobanks your data shows, not percentage alone
- Redsys vs direct bank paths — does the provider route through Redsys, direct ASPSP connections, or both? What changes in sandbox vs production?
- Retail vs business accounts — does verification and payment initiation work on the account types you onboard?
- Redirect vs embedded UX — what does the customer see on mobile for each major bank?
- Instant vs standard SEPA — when SCT Inst fails, what fallback timing do you communicate to treasury?
Run sandbox tests with real internal accounts at your top ten customer or borrower banks before shortlisting vendors. A provider optimised for UK open banking will not automatically feel native in Spain.
Regulatory context in plain terms
Spanish open banking sits on EU payment rules implemented nationally — customers must consent, strong authentication applies for access and payments, and regulated providers hold the licences to call bank APIs on your behalf. Spain transposed PSD2 later than many EU peers (Mastercard), which partly explains a smaller domestic TPP ecosystem than France or the Netherlands — international providers often passport services in instead.
For B2B buyers this means:
- You usually integrate a licensed partner rather than becoming a payment institution on day one
- Purpose and consent copy must match what you do (checkout vs lending vs verification)
- Data residency expectations are stricter in enterprise procurement — confirm EU hosting and subprocessors
The Banco de España supervises payment institutions and financial stability in Spain; the European Banking Authority sets the EU-wide payment-services framework your provider operates under. This is context for procurement, not a substitute for legal review.
Provider evaluation questions for the Spanish market
Use this checklist in RFPs and technical diligence — score answers with evidence, not slides. If you need a structured shortlist across markets, use our provider matching form to compare coverage for your bank list and use case.
Coverage and reliability
- Name the top 15 Spanish ASPSPs you support in production, with go-live dates
- Do you connect via Redsys, direct bank APIs, or both — and what is the failover path?
- What is your measured success rate for payment initiation on those banks (last 90 days)?
- How do you handle bank maintenance windows and degraded modes?
Products your roadmap needs
- Pay by Bank: mobile deep links, QR, desktop redirect behaviour per major bank
- Account verification: name–IBAN match rates on retail and business accounts
- AIS depth: transaction history length, categorisation for lending or reconciliation
- Payouts: outbound SEPA and Instant coverage for marketplace or lender disbursement
- Recurring: SEPA Direct Debit mandate support after first authenticated payment
Integration and ops
- Sandbox parity — do Spanish banks in sandbox match production behaviour?
- Webhook delivery guarantees, retries, and signing for finance automation
- Reference field rules compatible with Spanish invoice numbers and ERP imports
- Support SLAs in CET business hours for production incidents
Commercial and risk
- Pricing model for successful vs failed initiation attempts
- EU data residency, ISO 27001 / SOC 2, and subprocessors list
- Sector acceptance: marketplaces, lenders, insurers, SaaS — named in contract
- Exit terms and portability if you change provider after go-live
No single vendor fits every Spanish use case; matching depends on whether you optimise checkout conversion, lending data depth, or B2B payout reliability. See how to choose an open banking provider for a cross-market framework.
Common Spanish deployment patterns
E-commerce and marketplaces — Pilot Pay by Bank on high-AOV ES baskets with card fallback; add seller verification before scaling weekly payouts. Cross-read open banking for marketplaces.
SaaS and B2B platforms — Verify the cuenta on annual invoice setup; collect first payment via bank app; move renewals to direct debit where mandates are supported. See open banking for SaaS platforms.
Lenders — Income verification on supported banks first; expand affordability and collections once consent renewal is automated. See income verification open banking.
Multi-market EU expansion — If Spain follows France or Germany in your rollout, treat each country as a separate acceptance test. Open banking UK vs EU explains why UK and EU stacks diverge post-Brexit; open banking providers nordics shows the same discipline for northern Europe.
Frequently Asked Questions
What is open banking in Spain?
Open banking in Spain is regulated API access to Spanish bank accounts so businesses can verify accounts, initiate customer payments, and read consented transaction data — with customers approving in their banking app, usually via a licensed provider that connects through Redsys or direct bank interfaces.
Is open banking widely used in Spain?
Adoption is growing for Pay by Bank and account verification, but cards and Bizum still shape many consumer payment habits. Spain transposed PSD2 later than several EU peers and lacks a single national API standard like the UK — pilot on your customer bank mix rather than assuming Spain behaves like the Netherlands.
What is the difference between open banking and Bizum in Spain?
Open banking uses PSD2 APIs through licensed providers for merchant-controlled checkout, verification, and data access. Bizum is a bank-backed instant payment scheme accessed through consumer banking apps, strong for P2P and expanding in retail. They are related account-to-account rails but different integration and reconciliation paths.
Do I need a Spanish licence to use open banking?
Most non-bank businesses integrate a licensed open banking provider that holds the required EU authorisations. Your legal team confirms whether your specific model needs additional licensing beyond that partnership.
How is Spanish open banking different from France or Germany?
All three operate under EU payment rules, but Spain routes many banks through Redsys, shares a high card-online share, and has Bizum as a dominant consumer scheme — different from France's caisse networks or Germany's Sparkassen invoice culture. Test each market independently.
Which Spanish banks matter most for coverage?
Depends on your segment — consumer lenders care about retail neobanks and major high-street groups; B2B invoice platforms care about professional account support. List the banks your users actually hold and test those in sandbox, prioritising CaixaBank, BBVA, Santander, and Sabadell unless your data says otherwise.
Can open banking replace cards in Spain?
For many flows it supplements rather than replaces cards — especially where customers expect card habits or international buyers use non-Spanish banks. Most teams run dual rails with data-driven routing.
How do I evaluate open banking providers for Spain?
Demand named bank coverage, Redsys routing clarity, sandbox proof on your top institutions, success-rate data, business-account support, Instant payout honesty, EU hosting, and sector fit in contract. Weight criteria by your primary use case — checkout vs lending vs payouts.
Closing thought
Open banking Spain rewards specificity: name the banks your customers use, understand Redsys routing and Bizum's consumer role, and separate marketing coverage from production success rates. Once Spanish flows work, expand to the next EU country with the same discipline — not the assumption that one "EU" integration behaves identically everywhere.
Related articles
- Open Banking in France: Coverage and Provider Fit
France sits on many EU payment roadmaps — large banked population, strong mobile banking apps, and heavy B2B invoice volume — yet open banking France on a prov…
- Pay by Bank Netherlands: iDEAL to Wero Migration Guide
If you sell into the Netherlands, most of your online revenue probably arrives through iDEAL — bank-account checkout that Dutch shoppers treat as the default.…
- UK Open Banking Adoption: What 1 Billion Payments Means for B2B
If you sell into the UK and still treat pay-by-bank as a pilot, the scale numbers just moved again. On 30 July 2026, Open Banking Limited reported that the UK…